
Indians love gold, so much so that India is currently the largest gold holder. According to a report by the World Gold Council (WGC), total gold holdings in India are roughly valued at $2.4 trillion across an estimated 25,000 tons of gold.
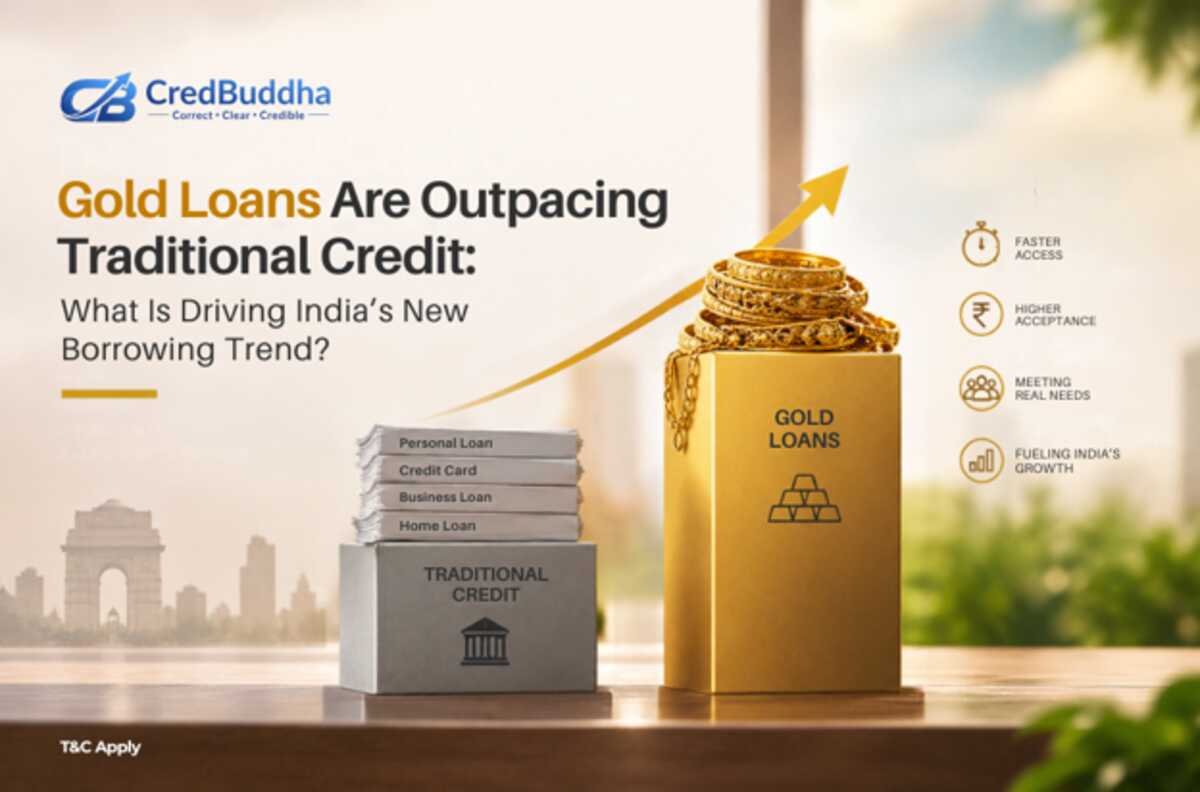
This has created a shift in the loan markets in India. A TransUnion CIBIL report stated that gold loans have become the second-largest retail credit product—rising 3.8 times since March 2022, from 5.9% to 11.1% in December 2025.
In this article, we will have a look at the reasons behind a rise in consumer preference for gold loans and the risks to be aware of.
What Is Driving India’s Shift to Gold Loans?
Several factors have led to an increase in gold loan applications in India. Given below are the major ones that we will have a look at:
- New RBI Directive: In April 2026, the Reserve Bank of India (RBI) updated their regulatory framework, increasing the loan-to-value (LTV) cap from 75% to 85% for loans up to ₹2.5 lakh and to 80% for loans of amounts between ₹2.5 lakh and ₹5 lakh. This allows consumers to borrow more without pledging additional gold.
- Increase in Gold Prices: Gold is internationally priced in dollars, and due to a weakening Indian rupee, consumers require more cash to buy the yellow metal, leading to a price spike. This, in turn, enables customers to apply for higher loan amounts. You can visit the CredBuddha website to explore their Gold Rate page and use the inbuilt gold loan calculator to determine the rate based on the gold you possess.
- Growing Preference for Secured Credit: Unsecured loans like personal loans require a high credit score and strong eligibility criteria for approval. Customers are slowly shifting to gold loans, as secured borrowing is possible with higher capital and lower interest rates available. The quick disbursal period has made gold loans a preferable option for both customers and small businesses.
- More Liquidity: With more financial awareness, customers, especially from tier-1 and tier-2 cities, are realising that they can raise capital without letting go of their gold ownership. This ensures that they do not need to sell their assets to meet immediate financial requirements.
- Increased Transparency Makes Gold Loan a Protective Option: Tightened RBI regulations ensure that lenders maintain more transparency in the secured borrowing sector. Financial entities need to clearly mention the charges, provide a fair market valuation of the pledged asset, and return the gold item to the customer within 7 days of full repayment.
What Are the Risks Borrowers Should Not Ignore?
Before applying for a gold loan, borrowers must acquaint themselves with the RBI directions and the risks involved. Some of them are mentioned below:
- RBI continuously monitors global gold prices. If they drop, so will the value of your pledged asset—causing the LTV to increase. You may have to pledge additional gold if the LTV ratio exceeds permissible limits.
- Failure to clear EMIs and respond to the lender’s notices on time allows the lender to auction your pledged gold items.
- The value of your gold is based on its intrinsic raw weight and purity. Additional costs like making charges are excluded.
- RBI caps the amount of gold items you can pledge. For example, the total limit for gold coins is 50 grams per borrower and 1 kg per person for gold ornaments.
- For a loan amount above ₹2.5 lakh, the bank will check your credit score and your capacity to repay the loan amount.
- You cannot use a gold loan to invest in gold-based financial assets like gold ETFs, mutual funds, and bars.
- Pledging your gold for multiple loans that exceed the threshold limit, you risk being flagged under the Anti-Money Laundering (AML) framework.
Frequently Asked Questions (FAQs)
- Why are gold loans growing rapidly in India?
Tightened RBI regulations, an increase in gold prices, and more financial awareness have led to more people applying for gold loans in India.
- Why are borrowers applying for gold loans instead of selling their gold?
Borrowers have realised that they can raise capital without having to sell their assets and lose their ownership. Once the EMI is repaid, they retain the pledged gold item.
- What will happen if I do not repay the gold loan?
In the event of your failure to repay the loan on time, the lender will auction your pledged gold item to recover the loan amount in accordance with the RBI norms.
- What should borrowers check for before applying for a gold loan?
Borrowers must check the interest rates, repayment tenure, applicable LTV, valuation methodology, and processing fees charged by the lender before applying for a gold loan. To find out more, visit the CredBuddha website.
- What trends define the usage of gold loans in India?
More people from tier-3 cities are applying for gold loans through digital channels such as mobile applications and prefer RBI-regulated moneylenders. Apart from that, the number of women borrowers has significantly grown to 39% in 2025 from 36% in 2022.